Inheritance Tax Planning in Croydon
Your Croydon home has likely grown in value far beyond what you paid for it. That growth is good news for your family, until HMRC takes 40% of it. I help Croydon residents structure their estates to minimize what goes to the taxman.
✓ 35+ Years Experience
✓ Fixed Fee Guarantee
✓ No Hidden Costs
Ask yourself: how many times should your family pay inheritance tax on your estate? Once? Twice? The answer should be zero.
Croydon has changed considerably over the years. Areas like South Croydon, Sanderstead, and Purley have seen steady property growth, while regeneration in the town centre has brought renewed interest across the borough.
Many Croydon residents who purchased homes decades ago now find their estates exceed the inheritance tax threshold by a significant margin. At 40% tax on everything above the allowance, your family could face a hefty bill at an already difficult time. I help Croydon families reduce their inheritance tax liability so more of your wealth goes to the people you care about.
Many Croydon residents who purchased homes decades ago now find their estates exceed the inheritance tax threshold by a significant margin. At 40% tax on everything above the allowance, your family could face a hefty bill at an already difficult time. I help Croydon families reduce their inheritance tax liability so more of your wealth goes to the people you care about.
Why Croydon Homeowners Need to Think About Inheritance Tax Now
Here's the situation many Croydon residents find themselves in:
You bought your home 20 or 30 years ago. At the time, £100,000 seemed like a lot of money. Today, that same property is worth £600,000, £700,000, maybe more depending on the road. You've also accumulated savings, perhaps some investments, and you have a pension.
Add it all up, and your estate is likely worth somewhere between £800,000 and £1.2 million. That puts you well above the inheritance tax threshold.
The basic threshold (nil rate band) is £325,000. If you're leaving your home to your children or grandchildren, you may get an additional £175,000 (residence nil rate band). That's £500,000 per person, or £1 million for a married couple.
Sounds like enough?
For some Croydon families, it is. For many others, it falls short. And the rules around these allowances are full of conditions that can reduce or eliminate them entirely.
The result: your family could owe HMRC a significant sum, payable within six months of your death, often before they've had time to grieve properly, let alone sell assets to raise the funds.
Plan your inheritanceYou bought your home 20 or 30 years ago. At the time, £100,000 seemed like a lot of money. Today, that same property is worth £600,000, £700,000, maybe more depending on the road. You've also accumulated savings, perhaps some investments, and you have a pension.
Add it all up, and your estate is likely worth somewhere between £800,000 and £1.2 million. That puts you well above the inheritance tax threshold.
The basic threshold (nil rate band) is £325,000. If you're leaving your home to your children or grandchildren, you may get an additional £175,000 (residence nil rate band). That's £500,000 per person, or £1 million for a married couple.
Sounds like enough?
For some Croydon families, it is. For many others, it falls short. And the rules around these allowances are full of conditions that can reduce or eliminate them entirely.
The result: your family could owe HMRC a significant sum, payable within six months of your death, often before they've had time to grieve properly, let alone sell assets to raise the funds.
What Happens If You Don't Plan
- A tax bill of £50,000, £80,000, sometimes over £100,000
- Pressure from HMRC to pay within six months
- No access to the estate's funds until probate completes
- Difficult conversations about selling the family home to cover the bill
- Mistakes in the calculations that trigger penalties or overpayment
The Mathematical Challenge of IHT for Croydon Families
Inheritance tax looks simple on paper. In practice, it's full of traps.
Let me give you a Croydon example. A widower in Purley owns a detached house worth £780,000. His late wife passed away three years ago and left everything to him. He has £95,000 in savings and a pension valued at £85,000. Total estate: £960,000.
He assumes he's fine. His wife's unused nil rate band transferred to him, giving him £650,000. Add the residence nil rate band of £350,000, and he's covered up to £1 million.
But here's where it gets complicated. He remarried last year. His new wife has two adult children from a previous marriage. He wants to leave her the house, but if he does, the residence nil rate band may not apply because the property isn't passing to his direct descendants.
Suddenly, his allowances drop from £1 million to £650,000. His taxable estate is now £310,000, and his family faces a bill of £124,000.
Inheritance tax planning isn't about knowing the rules. It's about knowing how the rules interact with your specific family situation. That's what I do.
Plan your inheritanceLet me give you a Croydon example. A widower in Purley owns a detached house worth £780,000. His late wife passed away three years ago and left everything to him. He has £95,000 in savings and a pension valued at £85,000. Total estate: £960,000.
He assumes he's fine. His wife's unused nil rate band transferred to him, giving him £650,000. Add the residence nil rate band of £350,000, and he's covered up to £1 million.
But here's where it gets complicated. He remarried last year. His new wife has two adult children from a previous marriage. He wants to leave her the house, but if he does, the residence nil rate band may not apply because the property isn't passing to his direct descendants.
Suddenly, his allowances drop from £1 million to £650,000. His taxable estate is now £310,000, and his family faces a bill of £124,000.
Inheritance tax planning isn't about knowing the rules. It's about knowing how the rules interact with your specific family situation. That's what I do.
How I Reduce Your Inheritance Tax Bill
I use a three-step approach with every client. It's designed to give you clarity without overwhelming you with jargon.
Step One: Your Vision
We have a meeting for up to 90 minutes. I'll ask about your family, your assets, your concerns, and what you want to achieve. This isn't a sales pitch. It's a conversation. By the end, I'll have a clear picture of where you stand and what options might be available.
Step Two: The Blueprint
I go away and do the detailed work. I research your specific circumstances, run the numbers, and identify the strategies that apply to you. I then write a report in plain English (no legal jargon) that explains what I recommend and why. Each recommendation includes a cost estimate. You'll receive this about a week before our next meeting.
Step Three: Implementation
We meet again to go through the report together. I'll answer your questions and we'll agree on what to implement and at what pace. From there, I handle the execution. Depending on your situation, implementation typically takes one to three months.
At the end of this process, you'll know exactly where you stand, what your family will receive, and what (if anything) will go to HMRC.
At the end of this process, you'll know exactly where you stand, what your family will receive, and what (if anything) will go to HMRC.
When we started, I asked how many times your family should pay inheritance tax on your estate. If you said zero, that's the goal we'll work toward.
Plan your inheritanceWith proper planning, many of my clients pay nothing. Others reduce their bill by tens or hundreds of thousands of pounds. Either way, you'll have certainty about what happens to your estate, and your family won't be scrambling to find cash for HMRC during an already difficult time.
If you're ready to get started, book a consultation.
Ready to begin? Take the first step and book your consultation
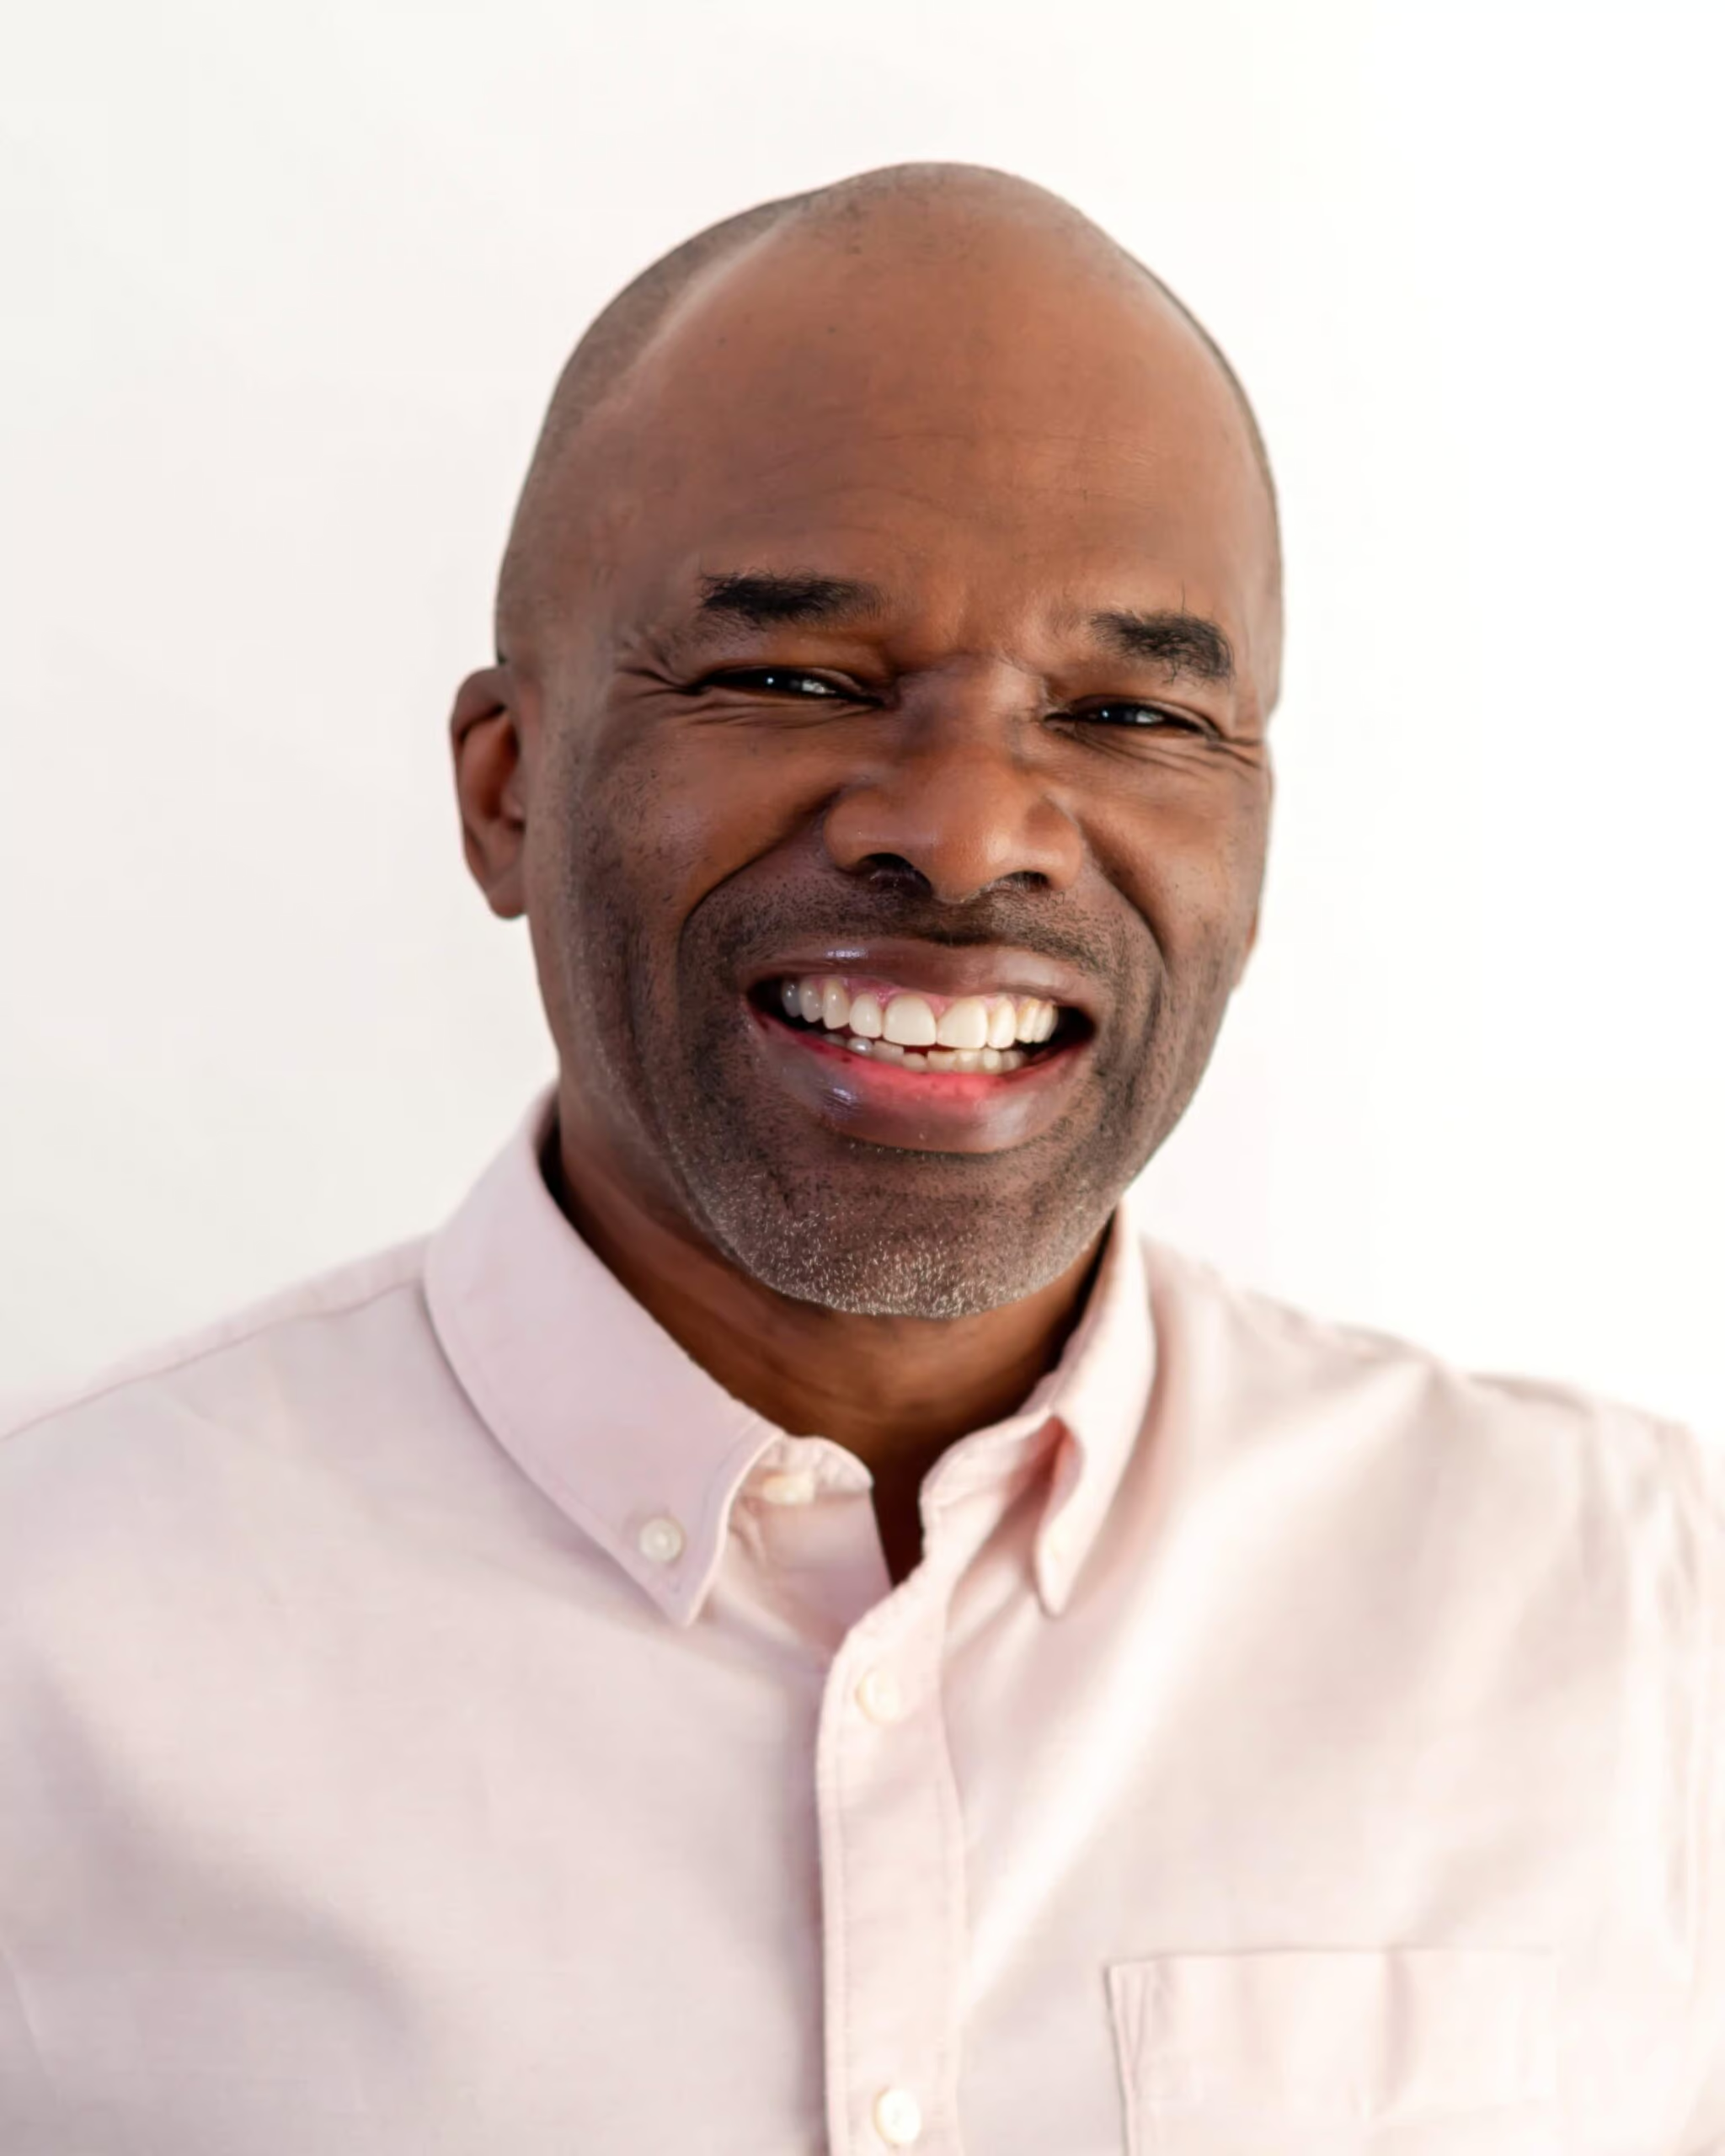
Meet Ade: Your Carshalton Inheritance Tax Specialist
I'm Ade, and I've spent 35 years helping families protect their estates from unnecessary taxation.
I work exclusively on estate planning, inheritance tax, and probate. I don't do conveyancing, divorce, or commercial law. This is my entire focus, and it means I've seen just about every situation you can imagine.
I work with clients across Croydon, from Sanderstead and Purley to Thornton Heath and Norbury, as well as throughout England and Wales.
My approach for Croydon clients
I limit the number of clients I take on each month. Your estate planning shouldn't feel like it's being processed on a conveyor belt.
When you work with me, you get my direct attention. I explain everything in plain English. I don't use jargon to make myself sound clever, and I don't rush you into decisions.
My goal is simple: make sure your family keeps as much of your wealth as legally possible, and make sure you understand exactly how that's going to happen.
I've helped thousands of families across the UK reduce or eliminate their inheritance tax bills. I'd like to help yours.
Book your consultationWhen you work with me, you get my direct attention. I explain everything in plain English. I don't use jargon to make myself sound clever, and I don't rush you into decisions.
My goal is simple: make sure your family keeps as much of your wealth as legally possible, and make sure you understand exactly how that's going to happen.
I've helped thousands of families across the UK reduce or eliminate their inheritance tax bills. I'd like to help yours.
Peace of Mind For Family Like Yours
I've worked with families across Croydon and beyond. Here's what some of them have to say.


Frequently Asked Questions
Your questions about Inheritance Tax answered
I own a house in Purley or Sanderstead. Will it be subject to inheritance tax?
It may well be. Houses in areas like Purley, Sanderstead and Shirley often run from £550,000 well past £750,000, which is above the £500,000 a single person can leave tax-free once the home goes to children. So the property alone can bring inheritance tax into range, and savings, pensions and investments are added on top. A married couple has more allowance to work with.
My Croydon flat is worth around £280,000. Is my estate below the inheritance-tax threshold?
The flat on its own sits below the £325,000 nil-rate band, so a town-centre leasehold flat around £280,000 does not cross the line by itself. But inheritance tax looks at everything you own together, so savings, a pension, a car and life insurance not written in trust all add up. It is worth totalling the whole estate rather than judging it on the property alone.
Croydon has a real two-tier property market. How does that affect my inheritance-tax planning?
It changes where you stand. Suburban houses in the south of the borough regularly cross the tax-free allowances, while town-centre flats often fall below them. So two Croydon families can have very different exposure, and the right plan depends on which side of that line you sit. I look at the whole estate before suggesting anything, so the advice fits your actual position rather than a borough average.
Can I pass my Croydon home to my children without inheritance tax?
The residence nil-rate band is built for that. Passing your main home to children or grandchildren adds up to £175,000 to your tax-free total, which is why a couple can reach £1 million between them. Many Croydon homes sit inside that, though the higher-value houses in the south of the borough can still leave a taxable slice worth planning for.
Take the next step in protecting your family's wealth
If you own property in Croydon and you're unsure whether your family will face an inheritance tax bill, let's have a conversation.
I'll give you a clear picture of where you stand and what your options are. No obligation, no pressure, just straightforward advice from someone who's been doing this for 35 years.
Book a consultation and let's see what we can do for your family.
Plan your inheritanceI'll give you a clear picture of where you stand and what your options are. No obligation, no pressure, just straightforward advice from someone who's been doing this for 35 years.
Book a consultation and let's see what we can do for your family.